
India’s solar manufacturing story is usually told through one number: gigawatts of capacity. It’s an easy number to announce, an easy number to compare year over year, and an easy number to use as evidence of industrial progress. It is also, on its own, a poor predictor of whether a manufacturing sector is actually competitive.
Capacity tells you what a set of factories could theoretically produce if everything ran perfectly. It says nothing about how much of that capacity is actually operating, how efficiently, at what yield, or whether the underlying process technology is keeping pace with global cost curves. India’s own manufacturing data illustrates this gap clearly — and the gap matters more, not less, as the sector matures.
The Capacity Number India Usually Leads With
By the end of 2025, India’s cumulative solar module manufacturing capacity had reached approximately 210 GW, according to Mercom India’s State of Solar PV Manufacturing in India 2026 report, with module capacity under the government’s Approved List of Models and Manufacturers (ALMM) List-I standing at around 173 GW. On paper, this looks like a manufacturing sector that has scaled dramatically — and in terms of module assembly capacity, it genuinely has.
But the same report puts India’s cell manufacturing capacity at only around 27 GW, with ALMM List-II cell capacity at roughly 26.5 GW — meaning that even at full utilisation, the vast majority of India’s announced module capacity would need to run on imported cells, primarily from China, to actually produce modules. Research from the Council on Energy, Environment and Water (CEEW) frames this starkly: nameplate solar cell manufacturing capacity forms only around 20 per cent of India’s module manufacturing capacity, meaning roughly 80 per cent of module output would need to depend on imported cells.
This single comparison — 210 GW of module capacity against 27 GW of cell capacity — is the clearest illustration available that “capacity” as a headline number obscures more than it reveals about actual manufacturing depth.
Nameplate Capacity Is Not Utilisation
Even within the segments where India does have strong capacity, announced GW figures say nothing about how much of that capacity is actually running. A factory can be capacity-rated at 5 GW/year and running at 60% utilisation because of order-book gaps, working-capital constraints, input shortages, or unplanned downtime — producing an effective 3 GW/year of actual output. Utilisation depends on demand visibility, financing costs, and operational discipline, none of which are captured by a capacity announcement.
The Indian solar cell supply situation adds a second layer to this: even where cell capacity does exist, much of it has faced tight availability relative to demand, a dynamic covered in more detail in Websol’s article on India’s solar cell supply crunch. A capacity figure that looks adequate on paper can still translate into a procurement risk in practice if utilisation, yield or input availability don’t line up with it.
Yield: The Number That Turns Capacity Into Real Output
Nameplate capacity assumes every wafer that enters a line comes out as a sellable cell. In reality, no line achieves that. The share of processed material that becomes sellable, in-specification product — yield — is what actually converts theoretical capacity into real, monetisable output. Two factories with identical announced capacity can have very different real output and cost structures depending on their yield discipline, a dynamic explored in depth in Websol’s article on how solar cells are manufactured step by step, which lays out where losses accumulate through the production sequence.
This is why capacity announcements should be read as an upper bound, not a forecast. India’s cell manufacturing base includes lines at very different points on their yield-maturity curve — some running mature, well-optimised processes, others still in the ramp-up period that follows a new commissioning, which industry reporting suggests can take 18 to 24 months to reach stable yields. Aggregate national capacity figures blend all of these together into a single number that flatters the newest, least-proven additions as much as the most mature ones.
Cost Per Watt: Where Utilisation and Yield Actually Show Up
The commercial consequence of low utilisation and low yield is straightforward: higher cost per watt, for a given level of capital investment. This matters directly for India’s competitive position, since research comparing Indian and Chinese solar manufacturing costs has found that higher operating costs — driven by energy costs and lower labour productivity — make solar module manufacturing in India roughly 9 percent more costly than in China, even where investment costs are broadly comparable. Utilisation and yield gaps compound that structural cost disadvantage rather than offsetting it. For project developers, this cost dynamic ultimately flows into the levelised cost of electricity calculations covered in Websol’s guide to LCOE.
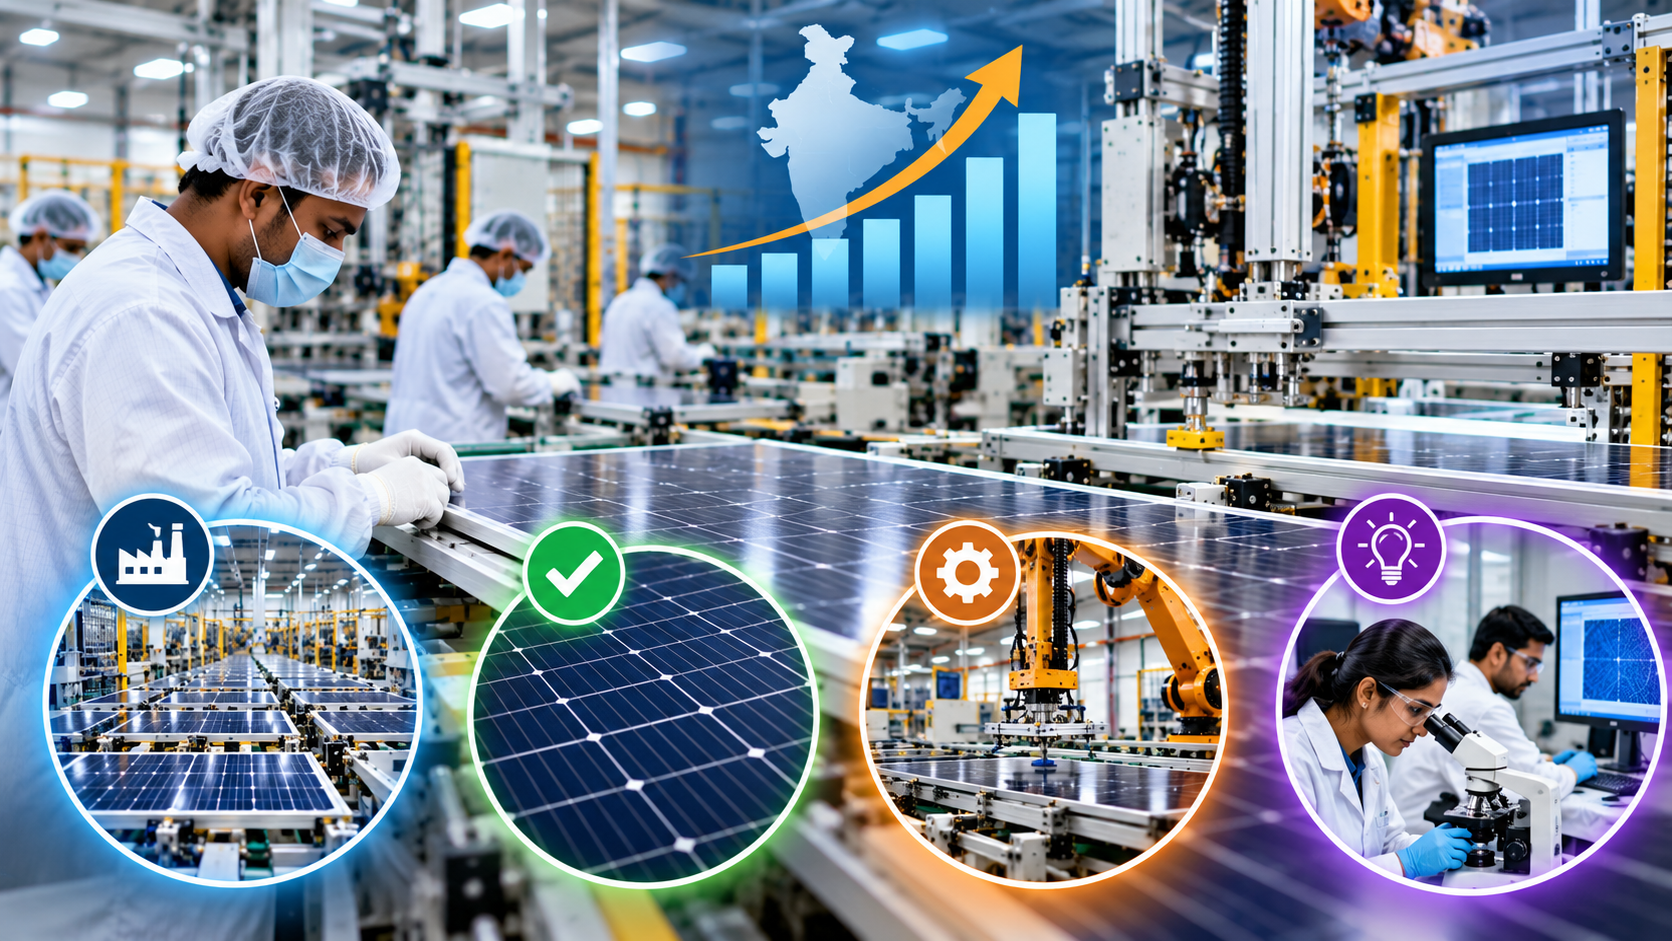
R&D: The Variable Capacity Numbers Don’t Capture at All
Perhaps the least visible gap in India’s manufacturing capacity story is R&D depth — investment in process improvement, next-generation cell architectures, and the kind of incremental efficiency gains that separate a mature manufacturing base from one that is simply assembling licensed or imported process technology at scale.
Capacity growth driven primarily by adding more lines of an existing, externally sourced process is a different achievement than capacity growth driven by improving the process itself. India’s rapid capacity expansion has been real and substantial, but the sector’s long-term competitiveness depends on whether that expansion is paired with genuine investment in process R&D, automation, and next-generation technology readiness — not just on replicating existing lines at larger scale. This is one of the more consequential open questions in India’s future of solar manufacturing, and it connects directly to the country’s broader ambitions to move from cell manufacturer to global exporter.
Automation and Workforce Skills: The Operational Layer Beneath R&D
Between raw capacity and long-term R&D sits a more immediate lever: how well existing lines are operated. Automation — in material handling, in-line testing, and process control — directly improves both yield and utilisation by reducing variability and unplanned downtime, a dynamic explained in Websol’s piece on how automation is reducing solar production costs. Workforce skill depth compounds this: an experienced operations team catches process drift earlier and troubleshoots faster than a newly trained one, which matters disproportionately during the ramp-up periods that accompany rapid capacity expansion.
Supply-Chain Resilience: Capacity’s Silent Dependency
Even a factory running at excellent yield and utilisation is only as resilient as its input supply chain — polysilicon, wafers, silver paste, and specialised equipment, much of which India still imports. The government scheme support built around domestic manufacturing, covered in Websol’s article on solar cell manufacturing government schemes and supply chain, is explicitly designed to close this dependency over time — but supply-chain depth, like R&D depth, doesn’t show up in a capacity announcement at all.
A Better Framework for Assessing Manufacturing Strength
Metric | What headline capacity misses |
Utilisation | How much of the announced capacity is actually running |
Yield | How much of what’s processed becomes sellable output |
Cost per watt | Whether that output is produced competitively |
R&D depth | Whether the process itself is improving, not just scaling |
Supply-chain resilience | Whether upstream inputs can support sustained output at scale |
Workforce and automation maturity | Whether operational discipline supports consistent quality over time |
None of these replace capacity as a useful number — a country or company genuinely does need physical capacity to compete. But capacity is a necessary condition for manufacturing strength, not a sufficient one, and treating it as the primary scorecard risks mistaking scale for competitiveness.
Key Takeaways
- India’s ~210 GW of module capacity sits against only ~27 GW of cell capacity, illustrating how capacity figures can mask structural gaps.
- Utilisation (how much capacity actually runs) and yield (how much of what runs becomes sellable product) both convert theoretical capacity into real output.
- Indian module manufacturing costs run roughly 9% above China’s on a like-for-like basis, driven by energy costs and labour productivity, not investment cost.
- R&D depth and supply-chain resilience are largely invisible in capacity announcements but matter as much for long-term competitiveness.
- A more complete assessment of manufacturing strength requires utilisation, yield, cost, R&D and supply-chain metrics alongside capacity.