
“Competitive” gets used loosely in solar manufacturing discussions — sometimes meaning cheapest, sometimes meaning highest efficiency, sometimes meaning largest scale. None of those alone is a reliable predictor of whether a factory can actually win and retain business against global suppliers over a multi-year horizon. Competitiveness is closer to a portfolio of factors that reinforce or undermine each other, and a factory that is strong on one dimension but weak on several others tends to lose ground once market conditions shift.
This article sets out a practical framework — not a ranking of countries, but a structured way to evaluate what a solar manufacturer actually needs to compete globally, and where India’s current position sits against it.
Energy Cost: The Input That Compounds
Solar cell and wafer manufacturing is energy-intensive, particularly at the furnace and deposition steps. Energy cost differences between manufacturing hubs don’t just affect a single line item — they compound across every production step that involves heating, cooling or plasma processing, which is most of the cell manufacturing sequence. A factory operating in a region with higher industrial electricity tariffs starts every cost comparison at a structural disadvantage that automation and scale can offset but rarely fully erase.
Labour Productivity: Automation’s Real Value
Labour cost per worker is one thing; labour productivity — output per worker-hour — is the number that actually matters for cost per watt. This is where automation earns its return. Automated material handling, in-line testing and process control reduce the labour hours needed per unit of output while also reducing the yield losses associated with manual handling variability, a dynamic explained in Websol’s article on how automation is reducing solar production costs. Research comparing Indian and Chinese solar manufacturing costs has specifically identified lower labour productivity, alongside higher energy costs, as a driver of India’s roughly 9% cost disadvantage in module manufacturing relative to China — underscoring that this is not primarily a wage-rate issue but a productivity-per-worker issue that automation and process maturity are best positioned to close.
Yield and Equipment Utilisation: Converting Capacity Into Cost Advantage
A factory’s real unit cost depends on how much of its processed material becomes sellable, in-specification product, and how much of its available production time is actually used. These two factors — yield and utilisation — determine whether announced capacity translates into competitive cost per watt, a relationship explored in more depth in Websol’s article on how solar cells are manufactured. A factory with excellent equipment but mediocre process discipline will lose a cost competition to a factory with more modest equipment but tighter yield control.
Raw Material Cost and Supply-Chain Localisation
Polysilicon, wafers, and silver paste are the dominant material costs in cell manufacturing, and a factory’s exposure to global price volatility in these inputs — particularly silver, which has seen sustained price pressure — is a direct competitiveness factor. Manufacturers actively reducing silver consumption per cell through finer busbar designs and paste optimisation, as described in Websol’s article on why silver matters in solar cell manufacturing, are directly improving their cost competitiveness independent of scale or automation. Supply-chain localisation — sourcing critical inputs domestically rather than through import-dependent chains — reduces both cost volatility and lead-time risk, which matters as much for reliability of delivery as for headline cost.
Technology and Process Innovation
Competitiveness is not static. A factory that adopted the most cost-effective technology available five years ago (Mono PERC) can find itself at a disadvantage today against factories that have moved to TOPCon or HJT, which offer better efficiency and lower degradation. India’s own manufacturing base illustrates the scale of this shift: roughly 70% of installed module capacity is now TOPCon-based. But technology adoption alone isn’t the whole story — process innovation within a given technology (tighter process windows, better in-line testing, incremental efficiency gains) is what separates factories running the same nominal technology at meaningfully different cost and quality levels.
Quality Systems: The Competitiveness Factor That’s Easy to Underrate
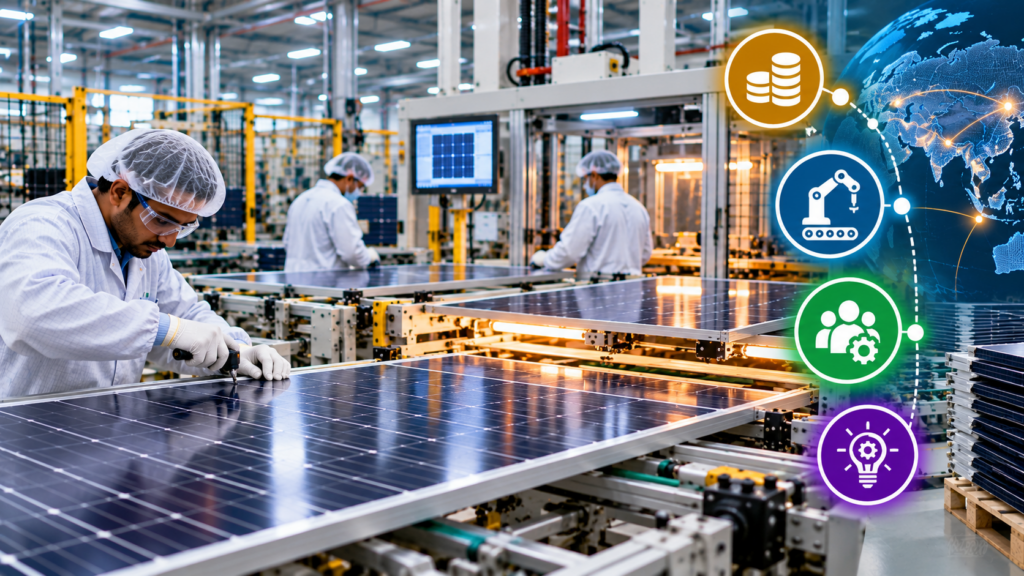
A factory can be cost-competitive on paper and still lose international business if its batch-to-batch consistency and defect detection systems aren’t robust enough to satisfy global buyers, who typically demand tighter quality documentation than domestic buyers. This is where systematic EL testing, binning discipline and PID/LID characterisation — covered in Websol’s article on solar cell quality beyond efficiency — function as a competitiveness factor in their own right, not just a compliance requirement. Export buyers in particular tend to weight quality-system maturity heavily in supplier selection, because the cost of a field failure discovered after shipment is far higher than the cost of catching it in-line.
Workforce Skills: The Compounding Asset
Automation reduces the need for manual labour in routine tasks, but it increases the value of skilled process engineers who can interpret automated system data, diagnose drift, and continuously refine process parameters. A workforce with deep, accumulated experience on a specific production line catches problems earlier and resolves them faster than a newly assembled team — this is one of the reasons rapid technology transitions carry a real productivity cost during the retraining period, and why workforce continuity is itself a competitiveness asset that doesn’t show up in capacity or cost figures.
Scale: Necessary, Not Sufficient
Scale matters because it allows fixed costs — R&D, quality infrastructure, senior process engineering talent — to be spread across more output, improving unit economics. But scale without yield discipline, quality systems and process innovation simply produces more output at the same (or worse) cost structure, not a genuinely more competitive one. This is why capacity figures alone are a poor proxy for competitiveness, a point developed further in Websol’s article on the future of solar manufacturing in India.
Financing Cost and Access
Cell and module manufacturing is capital-intensive, and the cost of capital directly affects how quickly a manufacturer can invest in the automation, quality systems and technology upgrades needed to stay competitive. Manufacturers with access to lower-cost financing — whether through government-backed schemes, export credit, or stronger balance sheets — can invest through market downturns in ways that thinly-capitalised competitors cannot, which compounds into a durable competitiveness gap over time.
Export Logistics
For manufacturers targeting international markets specifically, logistics cost and lead time to key ports and shipping routes are a real, if less discussed, competitiveness factor. A factory with excellent unit economics but poor logistics access to major export markets faces a landed-cost disadvantage that domestic-market competitiveness metrics don’t capture.
Bringing the Framework Together
|
Factor |
What it determines |
Where it’s easy to underrate |
|
Energy cost |
Baseline cost structure |
Compounds across most process steps |
|
Labour productivity |
Real cost per watt, not wage rate |
Automation’s actual return depends on this, not headcount reduction alone |
|
Yield & utilisation |
Whether capacity becomes real, sellable output |
Rarely disclosed publicly, unlike capacity figures |
|
Material cost & localisation |
Exposure to input price volatility |
Silver cost specifically, given recent price trends |
|
Technology & process innovation |
Whether the process itself improves over time |
Easy to conflate with simply adopting newer equipment |
|
Quality systems |
Ability to win and retain export business |
Often treated as compliance rather than competitiveness |
|
Workforce skill |
Speed of problem diagnosis and resolution |
Doesn’t show up in any capacity or cost announcement |
|
Scale |
Fixed-cost absorption |
Only useful when paired with yield and quality discipline |
|
Financing access |
Ability to invest through cycles |
Determines who can sustain R&D and automation investment |
|
Export logistics |
Landed cost in target markets |
Separate from domestic manufacturing competitiveness entirely |
Where This Leaves Indian Manufacturers
India has made genuine progress on several of these dimensions — most visibly technology adoption (the TOPCon shift), policy-supported scale, and growing quality-system maturity, an area explored across Websol’s guides on Indian solar cell manufacturers and supplier evaluation. The more persistent gaps — energy cost, labour productivity, and full upstream supply-chain localisation for polysilicon and wafers — are structural and will take longer to close than capacity expansion has taken.
Key Takeaways
- Global competitiveness in solar manufacturing depends on a portfolio of factors, not any single metric like cost, capacity or efficiency alone.
- Energy cost and labour productivity are the two structural factors most often cited in India-China cost comparisons.
- Yield, utilisation and quality-system maturity convert raw capacity and technology adoption into actual competitive advantage.
- Workforce skill and financing access are less visible but genuinely compounding competitiveness assets.
- Scale is necessary but not sufficient — it only improves competitiveness when paired with process discipline.
 ” and all products and logos denoted with trade mark are trademarks of Websol Energy System Limited. This trade mark may not be used in connection with any product or service that is not a Websol Energy System’s product, functions or service.